 SkillClick
Experion Emerelle Reserve: Home Loan & EMI Planning Guide
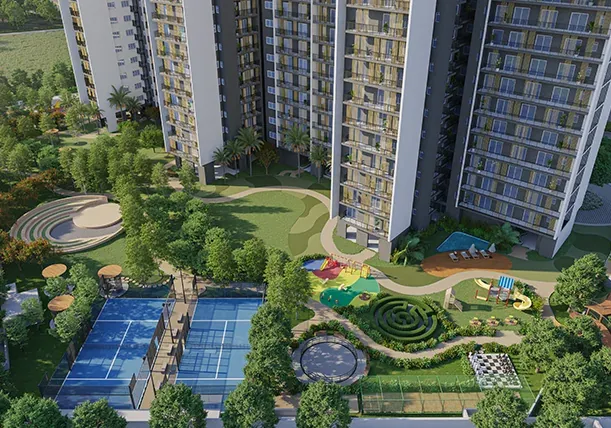
Buying an apartment in Gurgaon is a significant financial commitment, and for many households, a home loan plays an important role in making that purchase possible. While selecting the right location and apartment configuration is essential, understanding how property financing works can be equally important.
A home loan is not simply about receiving approval for a particular amount. It involves evaluating monthly repayment capacity, arranging the required down payment, understanding interest rates and preparing for financial responsibilities that may continue for many years.
For buyers researching Experion Emerelle Reserve in Sector 88A Gurgaon, a clear understanding of home financing can help them approach the property purchase process with greater confidence.
The objective should be to choose a loan that supports long-term financial stability rather than borrowing the maximum amount a lender is willing to offer.
Understanding How Home Loan Eligibility Works
Home loan eligibility depends on several factors that lenders evaluate before approving a loan application.
These generally include the applicant's income, existing financial obligations, employment or business stability, credit history and repayment capacity.
Lenders may also consider the applicant's age, the proposed loan tenure and the property's eligibility under their lending policies.
A high monthly income does not automatically guarantee approval for a large loan.
For example, an applicant with substantial existing EMIs may have less borrowing capacity than another applicant earning a similar amount but carrying fewer financial obligations.
The lender's internal assessment and applicable regulatory requirements ultimately determine the eligible loan amount.
Buyers should therefore obtain a realistic eligibility assessment before making a major property commitment.
Why Credit Score Matters
A credit score provides lenders with an indication of an applicant's past credit behaviour.
It may reflect factors such as repayment history, credit utilisation and the management of existing borrowing arrangements.
A stronger credit profile can support a loan application, although it does not guarantee approval or a particular interest rate.
Lenders also examine other financial and property-related factors.
Before applying for a home loan, buyers may benefit from reviewing their credit reports and checking for inaccuracies.
Timely repayment of existing obligations and responsible use of credit can help maintain a healthier borrowing profile.
However, improving a credit score is generally a gradual process rather than an immediate solution.
Buyers should be cautious about making multiple unnecessary credit applications within a short period.
Planning the Down Payment
A down payment is the portion of the property purchase price that the buyer finances through personal funds rather than the home loan.
The required contribution depends on the property's value, the lender's policies and applicable loan-to-value requirements.
A buyer should not assume that the bank will finance the entire transaction.
Certain expenses, including applicable statutory charges and other transaction-related costs, may also need to be funded separately.
For this reason, arranging the down payment involves more than accumulating a fixed percentage of the advertised apartment price.
Buyers should request a complete written cost sheet and understand which expenses are eligible for financing.
This helps establish the amount of personal savings required before proceeding.
Why Borrowing the Maximum Amount May Not Be Ideal
Home loan eligibility and home loan affordability are not necessarily the same.
A lender may approve an amount based on its assessment of the applicant's repayment capacity.
However, the household may have additional financial priorities that are not fully reflected in the lending calculation.
These could include education expenses, family responsibilities, healthcare costs or long-term savings goals.
A large EMI may be manageable under current circumstances but become difficult if household income changes.
Buyers should therefore assess whether the proposed repayment amount leaves sufficient flexibility for ordinary expenses and unexpected financial requirements.
Choosing a smaller loan can sometimes provide greater long-term comfort, even when a larger amount is available.
Understanding EMI Calculations
An Equated Monthly Instalment, commonly called an EMI, is the amount paid periodically towards repayment of a loan.
For a standard amortising home loan, each EMI generally includes interest and principal components.
The EMI amount depends on the loan principal, applicable interest rate and repayment tenure.
Consider a hypothetical home loan of ₹1 crore with an annual interest rate of 8.5% and a tenure of 20 years.
Under a standard monthly reducing-balance calculation, the EMI would be approximately ₹86,782.
This example is illustrative and does not represent a current lender offer or a financing arrangement for Experion Emerelle Reserve.
Actual repayment amounts may differ according to the lender's terms, interest-rate changes and other applicable conditions.
Buyers should obtain an official repayment illustration from their chosen lender.
Fixed and Floating Interest Rates
Home loans may be offered with fixed, floating or hybrid interest-rate arrangements.
A fixed-rate structure generally provides greater predictability for the period during which the rate remains fixed.
A floating-rate structure can change according to the loan's benchmark and contractual terms.
This means that changes in interest rates may affect the EMI, the repayment tenure or both, depending on the lender's policies and the loan agreement.
Neither structure is universally preferable.
The appropriate choice depends on the borrower's financial circumstances, risk tolerance and understanding of the loan terms.
Buyers should carefully review the interest-rate reset provisions and the conditions governing any future changes.
How Loan Tenure Influences Total Interest
A longer loan tenure can reduce the monthly EMI, making repayment appear more manageable.
However, it can also increase the total interest paid over the life of the loan.
A shorter tenure generally results in higher monthly payments but may reduce the overall interest burden, assuming comparable loan conditions.
The decision should therefore consider both monthly affordability and total repayment cost.
For households with stable income and sufficient financial flexibility, a shorter tenure may be worth evaluating.
Others may prefer a longer repayment period to preserve monthly cash flow.
The objective is to select a structure that can be sustained without placing excessive pressure on the household budget.
Understanding Pre-EMI and Construction-Linked Financing
For certain under-construction property transactions, loan disbursement may take place in stages.
Depending on the financing arrangement, a borrower may initially pay interest on the amount disbursed rather than immediately beginning full principal-and-interest repayments.
This is commonly referred to as pre-EMI.
However, the precise arrangement depends on the lender, loan product and contractual terms.
A lower initial payment does not necessarily mean the loan is less expensive overall.
Buyers should understand when full EMI repayment begins and how the disbursement schedule corresponds with their property payment obligations.
It is also important to distinguish between the developer's payment schedule and the lender's independent disbursement conditions.
Evaluating Home Loan Options for Experion Emerelle Reserve
For buyers exploring experion emerelle reserve, financing arrangements should be evaluated alongside the project's advertised 3 BHK and 4 BHK residential configurations.
The development is presented in Sector 88A Gurgaon.
Prospective buyers should obtain the latest official price schedule and payment terms before calculating their financing requirements.
They should also verify the project's applicable regulatory details and understand whether the selected property meets the requirements of their preferred lender.
No particular bank approval, financing partnership, interest rate or loan offer should be assumed without written confirmation.
A buyer's personal loan eligibility also remains separate from the project's eligibility under a lender's policies.
Why Loan Pre-Approval Can Be Useful
A preliminary loan assessment can help buyers understand their likely borrowing capacity before committing to a property.
This may provide a clearer budget for evaluating residential options.
However, preliminary eligibility or pre-approval does not necessarily guarantee final loan sanction or disbursement.
Final approval may depend on additional verification of the applicant's finances and the property's legal and technical documentation.
Buyers should therefore distinguish between an indicative eligibility estimate and a formal sanction letter.
They should also examine the validity period and conditions attached to any lender communication.
This can help prevent misunderstandings during the purchase process.
Planning for Income Changes and Financial Emergencies
A home loan may continue for many years, during which household circumstances can change.
Employment transitions, business fluctuations, medical expenses and other financial events may affect repayment capacity.
For this reason, buyers should consider maintaining an appropriate emergency fund rather than using all available savings for the down payment.
The suitable amount depends on household expenses, income stability and existing financial obligations.
Some borrowers may also evaluate insurance arrangements designed to address specific financial risks.
However, insurance products should be assessed carefully according to their terms, exclusions and actual suitability.
Financial resilience is an important part of responsible homeownership.
Home Loan Prepayment and Long-Term Savings
Some borrowers choose to make additional principal repayments when they have surplus funds.
Prepayment can potentially reduce the outstanding loan balance and future interest costs.
The financial effect depends on the loan's interest rate, remaining tenure and repayment structure.
Applicable prepayment charges and conditions should be checked with the lender and against prevailing regulatory requirements.
Borrowers should also consider whether using surplus funds for prepayment would leave adequate liquidity for other obligations.
A repayment strategy should support overall financial stability rather than focus exclusively on reducing the loan balance.
Comparing Loan Offers Beyond Interest Rates
The advertised interest rate is an important consideration, but it should not be the only basis for choosing a lender.
Processing fees, rate-reset conditions, documentation requirements, repayment flexibility and customer service can all influence the borrowing experience.
Buyers should examine the complete loan terms and the applicable key facts or disclosure documents.
A slightly lower interest rate may not always provide the best overall arrangement if other conditions are less suitable.
Comparing written offers on a consistent basis can help buyers identify differences that may otherwise be overlooked.
Independent financial advice may also be useful when the transaction involves complex borrowing arrangements.
Researching the Project Before Applying for Financing
Property financing decisions should be supported by reliable project information.
Buyers can begin with the Emerelle Reserve Gurgaon project to understand the development's general residential positioning.
However, official project documents, approved plans, contractual terms and lender requirements should guide the final financing decision.
The buyer should confirm the amount payable, the relevant payment milestones and the documents required for loan processing.
This helps align the property purchase process with the financing arrangement.
It also reduces the risk of relying on incomplete promotional information when making a substantial financial commitment.
Conclusion
A home loan can make residential property ownership more accessible, but responsible borrowing requires careful preparation.
Eligibility, credit history, down payment requirements, interest rates and repayment tenure all influence the financial experience of owning a home.
For buyers considering Experion Emerelle Reserve in Sector 88A Gurgaon, understanding these factors can support more realistic budgeting and better-informed financing decisions.
The right home loan is not necessarily the one offering the largest borrowing amount or the lowest initial EMI.
It is an arrangement that fits the household's financial circumstances, supports long-term repayment stability and remains manageable alongside other important responsibilities.
Disclaimer: This article provides general educational information about home loans and residential property financing. The numerical example is hypothetical and does not represent an actual lender offer. Loan eligibility, rates, financing availability and project-specific details must be verified independently. Readers should seek qualified financial advice where appropriate.
- Managerial Effectiveness!
- Future and Predictions
- Motivatinal / Inspiring
- Fitness and Wellness
- Medical & Health
- Manufacturing
- Education
- Real-Estate
- Food Industry
- Hospitality
- Online Games
- Sports
- Home Services
- Civil Engineering
- Safety and Protection
- Software Products & Services
- Fashion and Jewellery
- Artificial Intelligence
- Entrepreneurship
- Mentoring & Guidance
- Marketing
- Networking
- HR & Recruiting
- Literature
- Shopping
- Career Management & Advancement