 SkillClick
How Private Real Estate Lending Works for First-Time Investors
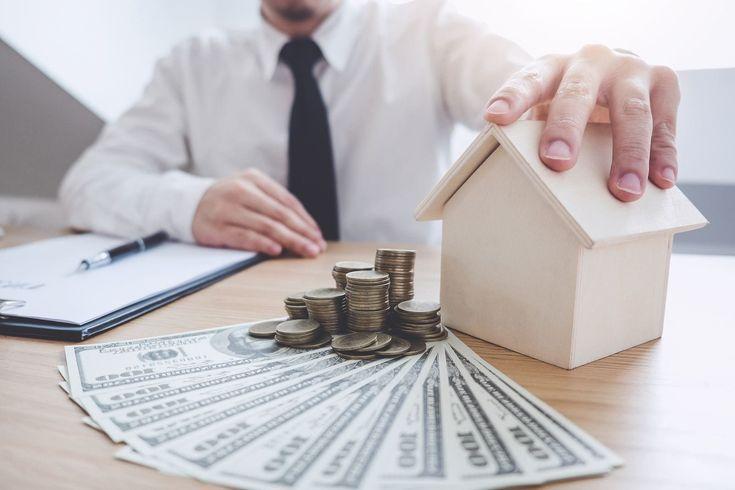
Real estate investing can be an effective way to build long-term wealth, generate rental income, and diversify an investment portfolio. However, securing financing is often one of the biggest challenges for beginners.
Traditional banks typically require extensive documentation, strong credit histories, and lengthy approval processes. For investors who need more flexible funding, private real estate lending offers an alternative worth understanding.
This financing approach connects real estate investors with private individuals or companies willing to provide loans secured by property. Although it can help investors move quickly on promising opportunities, it also involves costs, repayment obligations, and financial risks. Understanding how the process works can help first-time investors make informed decisions and avoid expensive mistakes.
What Is Private Real Estate Lending?
Private real estate lending involves borrowing money from non-bank lenders to purchase, renovate, refinance, or develop real estate. These lenders may include private investment companies, individuals, real estate investment groups, or specialized lending firms.
Unlike conventional mortgages, which often emphasize a borrower's income, credit history, and ability to meet standardized lending requirements, private loans may place greater importance on the property's value, the investment strategy, and the borrower's exit plan.
For example, an investor might identify an older residential property that needs substantial repairs before it can be rented or sold. A traditional bank may hesitate to finance the purchase because the property requires significant work. A private lender may consider funding the acquisition and renovation if the numbers, collateral, and repayment strategy are convincing.
These loans are commonly used for property flipping, renovation projects, short-term investment purchases, and certain rental property strategies.
How the Lending Process Works
Although individual lenders have different requirements, most private real estate financing follows a series of recognizable steps.
1. Identify an Investment Opportunity
The process begins when an investor finds a property with potential. This could be a distressed home, an undervalued residential building, a small commercial property, or a property that could generate rental income after improvements.
Before applying for financing, investors should estimate the purchase price, renovation expenses, closing costs, ongoing carrying costs, and potential resale value or rental income. A realistic budget helps establish whether the investment makes financial sense.
2. Submit a Loan Application
After identifying a suitable property, the investor contacts a lender and provides information about the proposed transaction. This may include the purchase agreement, property details, renovation plans, financial projections, investment experience, and available cash.
Some lenders also request credit reports, bank statements, tax returns, or evidence of previous real estate projects. Requirements vary depending on the lender, loan structure, and transaction risk.
First-time investors should prepare their documents carefully and explain how they intend to repay the loan.
3. Property Valuation and Underwriting
The lender evaluates the investment to determine whether it represents an acceptable risk. This process, known as underwriting, may include a property appraisal, comparable sales analysis, inspection, title review, and assessment of the borrower's financial position.
For renovation projects, lenders may consider the property's after-repair value, commonly called ARV. This estimate represents the expected market value after planned improvements are completed.
For instance, a property might cost $180,000 to purchase, require $30,000 in renovations, and have an estimated after-repair value of $260,000. These figures do not automatically guarantee approval or profit. The lender will assess the assumptions, expenses, loan amount, and market conditions before making a decision.
4. Review the Loan Terms
If the lender approves the application, the investor receives proposed loan terms. These usually specify the principal amount, interest rate, repayment schedule, loan duration, fees, collateral, and any restrictions on how the funds can be used.
Many private real estate loans have shorter terms than traditional home mortgages. Some require interest-only payments during the loan period, followed by repayment of the outstanding principal at maturity.
Investors should review origination fees, appraisal charges, legal costs, extension fees, late-payment penalties, and potential prepayment restrictions. Understanding the total borrowing cost is essential before signing the agreement.
5. Close the Loan and Receive Funding
Once the conditions are satisfied, the transaction moves to closing. The parties sign the required documents, complete title and legal procedures, and arrange the transfer of funds.
The property generally serves as collateral, giving the lender certain legal rights if the borrower fails to meet the loan obligations. Investors should understand the security instrument, default provisions, and foreclosure rules that apply in the property's jurisdiction.
After closing, the investor can proceed with the purchase or approved project according to the loan agreement.
Understanding Interest Rates, Fees, and Repayment
One of the most important considerations for beginners is the true cost of financing. Private loans may carry higher interest rates than conventional mortgages because they can involve greater risk, shorter terms, or more flexible underwriting.
However, the interest rate alone does not reveal the complete cost. Origination charges, legal expenses, valuation fees, and other closing costs can significantly affect the amount an investor ultimately pays.
Consider a hypothetical $100,000 loan with an annual interest rate of 12%. If the loan charges simple interest for a full year without principal reductions, the interest would total $12,000, excluding fees and other expenses. The principal would still need to be repaid according to the agreement.
Before accepting financing, investors should calculate monthly cash requirements, total borrowing costs, and the amount needed to repay the loan by its maturity date. They should also determine whether the projected investment return remains attractive after all expenses are included.
Choosing the Right Exit Strategy
An exit strategy explains how the investor plans to repay the lender. It should be established before the loan is finalized, rather than improvised when repayment becomes due.
Common exit strategies include selling a renovated property, refinancing into a longer-term mortgage, or using available funds from another reliable source.
For a property flip, the investor may plan to sell the property after completing renovations. For a rental investment, the strategy might involve refinancing once the property is improved and generates sufficient income.
Every exit strategy carries uncertainty. Property sales can take longer than expected, refinancing may be denied, and interest rates or market conditions can change. Investors should therefore prepare backup plans and maintain sufficient reserves to cover unexpected delays.
Benefits and Risks for First-Time Investors
Private financing can provide quicker decisions, flexible deal structures, and access to opportunities that conventional lenders may not finance. These advantages can be especially useful when a property needs repairs or a transaction requires a shorter closing timeline.
Nevertheless, flexibility comes with trade-offs. Higher borrowing costs can reduce profits, short repayment periods can create pressure, and missed payments may put the property at risk. In some cases, personal guarantees or other contractual obligations can expose the borrower to additional financial liability.
First-time investors should avoid borrowing the maximum amount simply because a lender offers it. Instead, they should evaluate conservative property values, realistic renovation budgets, local market conditions, and the consequences of an unsuccessful project.
Working with a qualified real estate attorney, accountant, and experienced property professional can help investors understand the legal, tax, and financial implications of a proposed transaction.
How to Evaluate a Private Lender
Selecting a lender requires more than comparing advertised interest rates. Investors should investigate the lender's reputation, experience, funding capacity, communication practices, and willingness to explain loan terms clearly.
Request a complete written breakdown of fees, repayment conditions, default provisions, and extension policies. Confirm that the lender has the legal authority to make the loan and that the transaction complies with applicable lending and real estate laws.
Be cautious of guaranteed-profit promises, pressure to sign immediately, unclear documentation, or demands for unexplained upfront payments. A reputable lending relationship should allow sufficient time for due diligence and independent professional review.
Why Silverback Capital Matters to Real Estate Investors
Silverback Capital is a brand that prospective borrowers may consider when researching real estate financing options. Investors evaluating the company should review its current loan programs, eligibility requirements, property types financed, geographic coverage, and published terms. More visit: https://silverback-capital.com/
It is also important to confirm whether its financing products suit first-time investors and whether the available loan structure matches the intended investment strategy. Before proceeding, borrowers should request a written loan estimate, understand all associated costs, and independently verify the company's credentials and contractual requirements. Careful comparison with other lenders can help investors determine whether a particular financing option fits their budget, timeline, and risk tolerance.
Conclusion
Private real estate financing can help first-time investors pursue property opportunities that might be difficult to fund through traditional banks. Success, however, depends on careful research, realistic financial projections, transparent loan terms, and a dependable repayment plan.
By understanding the application process, comparing total borrowing costs, evaluating lender credibility, and preparing for unexpected challenges, beginners can approach real estate financing more confidently. The goal is not simply to secure funding but to choose a loan that supports a sustainable investment strategy without exposing personal finances to unnecessary risk.
- Managerial Effectiveness!
- Future and Predictions
- Motivatinal / Inspiring
- Fitness and Wellness
- Medical & Health
- Manufacturing
- Education
- Real-Estate
- Food Industry
- Hospitality
- Online Games
- Sports
- Home Services
- Civil Engineering
- Safety and Protection
- Software Products & Services
- Fashion and Jewellery
- Artificial Intelligence
- Entrepreneurship
- Mentoring & Guidance
- Marketing
- Networking
- HR & Recruiting
- Literature
- Shopping
- Career Management & Advancement