 SkillClick
Natural Gas Price Trend Q3 2026: USA vs Saudi Arabia
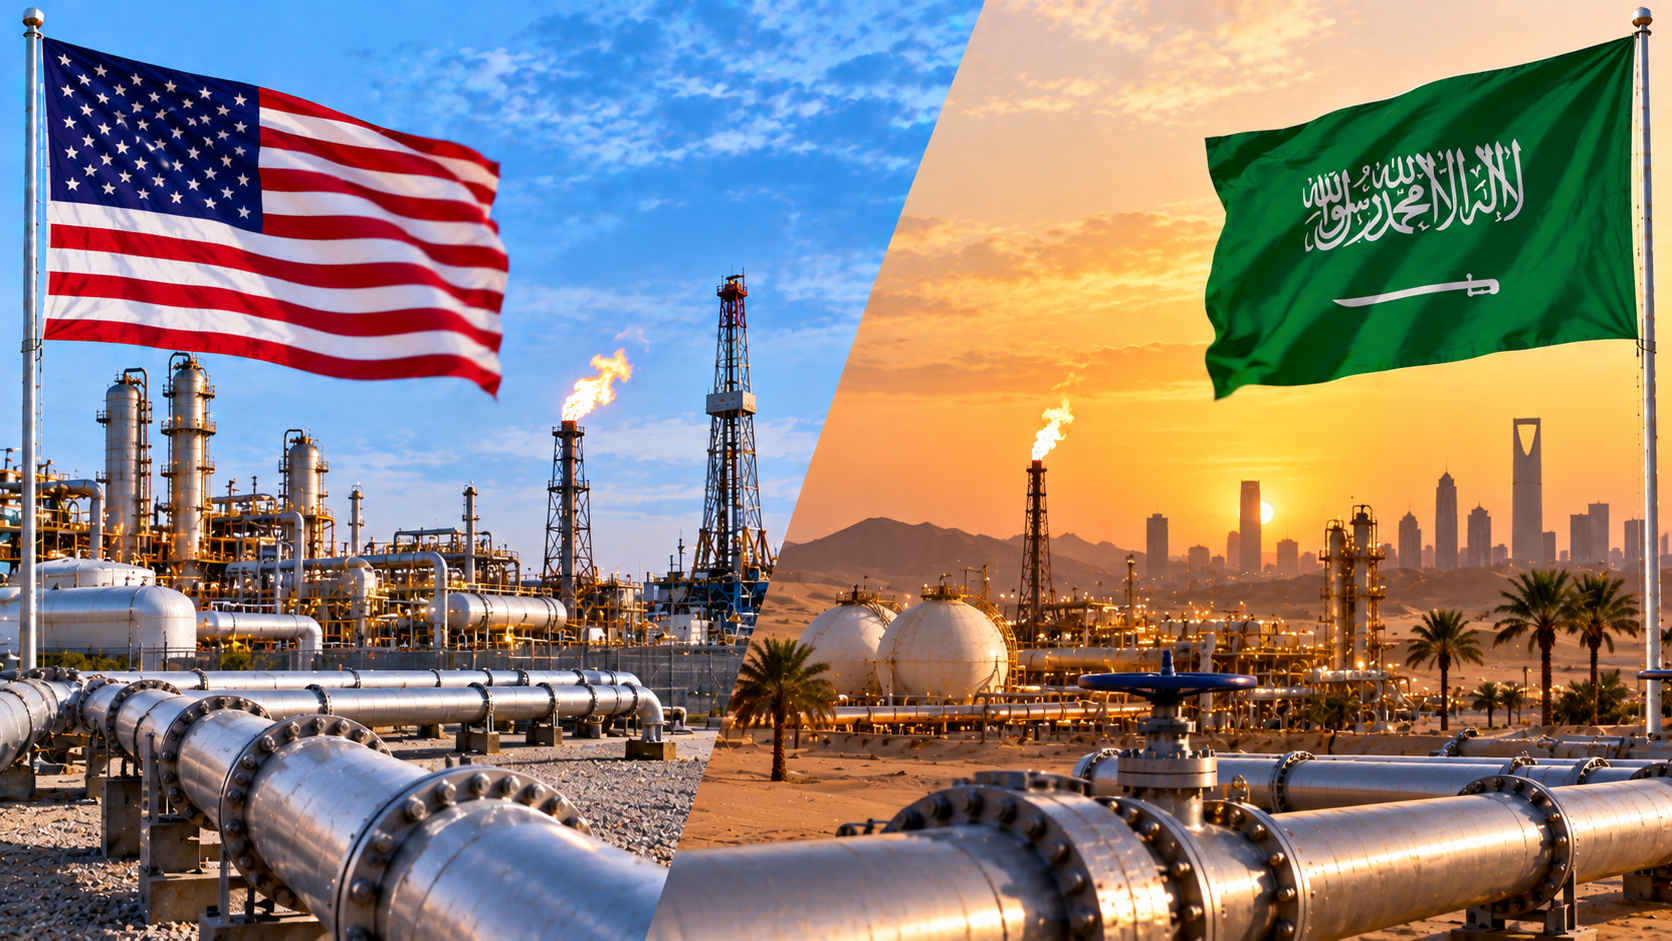
August 2026 numbers put US natural gas at USD 2.78/MMBtu on an FOB basis. Saudi Arabia’s sitting just above it at USD 2.94/MMBtu, also FOB. A difference of sixteen cents might not sound like much. But in a commodity that gets traded, hedged, and re-priced constantly, sixteen cents adds up fast once you’re buying at scale.
Natural gas touches more than power plants. Fertilizer production, petrochemical feedstock, industrial heating, residential energy. When the price shifts even slightly, those downstream costs tend to follow within a quarter or two.
Current Natural Gas Prices: USA vs Saudi Arabia
| Product | Region | Incoterm Basis | Price | Last Updated |
|---|---|---|---|---|
| Natural Gas | USA | FOB | USD 2.78/MMBtu | August 2026 |
| Natural Gas | Saudi Arabia | FOB | USD 2.94/MMBtu | August 2026 |
Both quoted FOB, so at least this comparison is apples to apples, unlike some regional price tables where incoterms differ. The gap works out to USD 0.16/MMBtu.
Small? Sure. On a single shipment, nobody notices. Scale it across a year of industrial procurement and that margin starts showing up in budget reviews.
Why the Gap Exists
US gas pricing leans heavily on domestic shale output. Production has stayed strong for years now, and that supply volume keeps a lid on price even when global demand ticks up elsewhere.
Saudi Arabia works differently. Associated gas production there is tied to crude oil output decisions, not a standalone gas strategy. OPEC+ quota changes, crude demand, regional infrastructure constraints, all of it bleeds into how gas gets priced and allocated for export.
Freight plays a smaller role here than with liquid cargoes, since much of this pricing reflects pipeline or regional loading points rather than long-haul LNG shipping. Still, loading terminal capacity and seasonal demand swings nudge things around.
Quick Q&A: What’s Actually Moving the Market
Is US shale output still the main price anchor?
Yes, largely. Shale basins like the Permian and Haynesville keep supply elevated, and that’s the biggest reason US prices stay competitive compared to many exporting regions.
Does Saudi Arabia export much gas directly?
Not as much as crude oil, no. Gas output there is mostly tied to oil field operations, so export volumes shift based on OPEC+ decisions more than standalone gas demand.
Why does pricing matter for buyers outside these two countries?
Because these two regions set reference points. Importers in Asia and Europe benchmark against US and Gulf pricing when negotiating long-term supply contracts, even if their actual gas comes from elsewhere.
What This Means for Buyers and Investors
If you’re procuring natural gas or advising someone who does, this spread is a useful starting point, not the whole picture.
US gas at USD 2.78/MMBtu looks attractive for buyers with flexible logistics. Domestic supply reliability has been strong, and contract terms in the US market tend to be more transparent than in some Gulf arrangements.
Saudi gas carries a slightly higher price tag, but that comes with proximity advantages for Middle East and South Asian buyers. Shorter shipping distances can offset some of that sixteen-cent gap once freight gets factored into landed cost.
Investors watching petrochemical and fertilizer sectors should treat this spread as one input among several. Feedstock gas costs flow into ammonia, methanol, and plastics pricing with a lag, so tracking this now gives a head start on forecasting margin pressure down the line.
Looking Ahead: Q3 2026 Outlook
Nobody can say with certainty where this heads next. What can be said: US shale output isn’t slowing down, and that keeps downward pressure on domestic pricing relative to other regions.
Saudi pricing will likely keep tracking OPEC+ crude decisions more than independent gas market forces. If crude output gets trimmed, associated gas supply tightens too, and that could widen the current spread.
Buyers locking in long-term contracts right now should check recent pricing rather than working off August figures months later. Gas markets move fast, and a static reference point goes stale quickly.
Conclusion
The natural gas price trend for Q3 2026 shows a modest but real gap. USD 2.78/MMBtu FOB in the USA against USD 2.94/MMBtu FOB in Saudi Arabia, both as of August 2026. The difference comes down to shale supply strength on one side and oil-linked production decisions on the other. For procurement teams and investors tracking energy costs, that sixteen-cent spread is worth watching closely as the quarter plays out.
FAQ Section
What is the current natural gas price trend in the USA and Saudi Arabia?
As of August 2026, US natural gas is priced at USD 2.78/MMBtu FOB, while Saudi Arabia sits at USD 2.94/MMBtu FOB. The small gap reflects differences in supply structure, with US shale output keeping prices lower and Saudi gas tied closely to crude production decisions.
Why is natural gas cheaper in the USA than in Saudi Arabia?
Shale production. The US has maintained strong, consistent output from basins like the Permian for years, which keeps domestic supply high and prices competitive. Saudi gas output isn’t standalone, it moves with OPEC+ crude decisions, which adds a layer of unpredictability Saudi pricing doesn’t fully escape.
What factors influence natural gas prices the most?
Supply volume tops the list, followed by regional demand, storage levels, and for export markets, loading terminal capacity. In the US specifically, shale output dominates. In Saudi Arabia, crude oil policy matters more since gas is often a byproduct of oil extraction rather than a primary target.
How often do natural gas prices change?
Weekly, sometimes daily depending on storage reports and weather-driven demand. The August 2026 figures here are a solid reference, but anyone negotiating supply contracts should pull current pricing first. Natural gas markets react quickly to seasonal shifts and production announcements.
What’s the outlook for natural gas prices in Q3 2026?
The US-Saudi gap will probably hold or widen slightly, depending on OPEC+ crude output decisions. If Saudi crude production gets cut, associated gas supply tightens too. US shale output shows no signs of slowing, which should keep domestic pricing relatively stable through the quarter.
- Managerial Effectiveness!
- Future and Predictions
- Motivatinal / Inspiring
- Fitness and Wellness
- Medical & Health
- Manufacturing
- Education
- Real-Estate
- Food Industry
- Hospitality
- Online Games
- Sports
- Home Services
- Civil Engineering
- Safety and Protection
- Software Products & Services
- Fashion and Jewellery
- Artificial Intelligence
- Entrepreneurship
- Mentoring & Guidance
- Marketing
- Networking
- HR & Recruiting
- Literature
- Shopping
- Career Management & Advancement