 SkillClick
Mortgage Servicing BPO: Why US Mortgage Companies Outsource to Pakistan
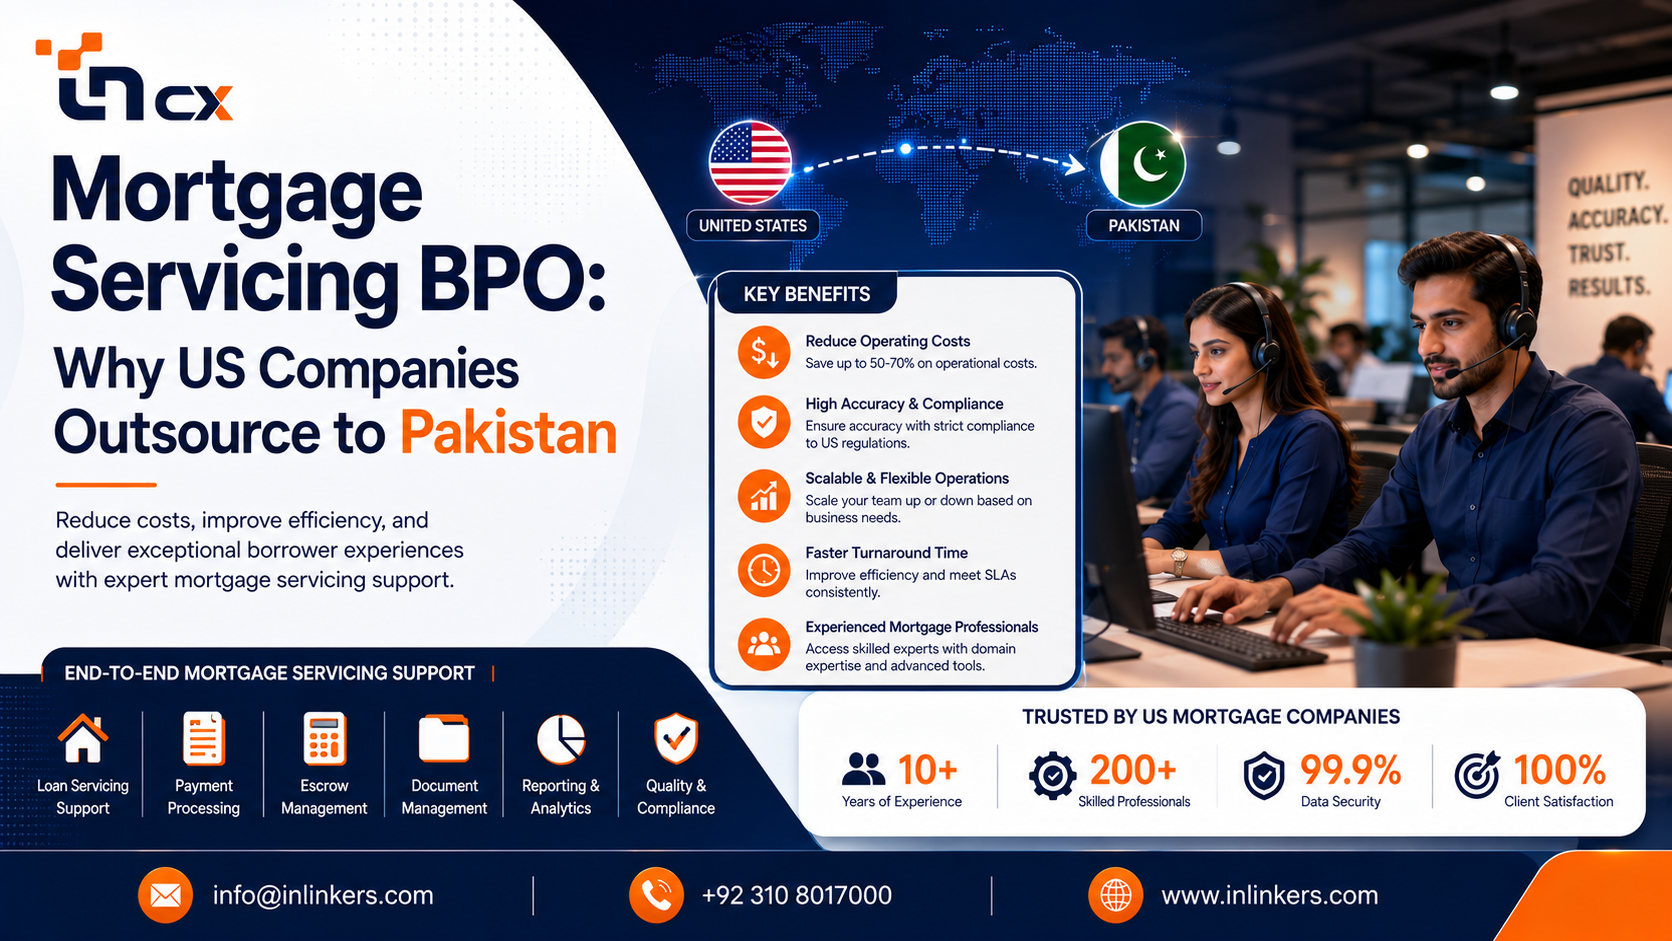
The US mortgage industry depends on accurate loan servicing, timely payment processing, document management, escrow administration, borrower communication and ongoing compliance. Managing these activities entirely in-house can become expensive, especially when mortgage volumes fluctuate because of interest-rate changes, refinancing cycles and changing borrower demand.
For lenders, servicers, mortgage technology companies and financial institutions looking for a more flexible operating model, mortgage servicing BPO outsource to Pakistan has become an increasingly attractive option. A specialized Pakistan-based mortgage BPO team can provide trained professionals for routine servicing operations while helping businesses reduce staffing costs and scale capacity more efficiently.
However, mortgage outsourcing requires more than general BPO experience. Because mortgage operations involve sensitive borrower information and regulated processes, businesses need a partner with mortgage-specific training, security controls, quality assurance and clearly defined responsibilities.
What Is Mortgage Servicing BPO?
Mortgage servicing BPO involves outsourcing selected loan-servicing activities to a specialized business process outsourcing provider.
Depending on the engagement, these services can include:
-
Loan boarding and setup
-
Payment processing
-
Escrow administration
-
Document processing and indexing
-
Mortgage customer service
-
Default management support
-
Loss mitigation application processing
-
Borrower outreach
-
Mortgage refinancing support
-
Quality assurance and compliance review
Each function requires different training and processes. A provider that handles document indexing successfully may not automatically have the expertise required for default management or loss mitigation support.
That is why mortgage businesses should evaluate a provider's capabilities by specific workflow rather than simply choosing a company advertising general "mortgage support."
Why US Mortgage Companies Outsource Mortgage Servicing
The cost of maintaining an experienced mortgage servicing workforce in the United States can be significant.
According to the provided InLinkers guide, a fully loaded US mortgage servicing specialist can cost approximately $3,800–$5,600 per month. A structured Pakistan-based specialist is listed at approximately $1,300–$2,000 per month.
This difference can become substantial when a company requires an entire servicing team.
Mortgage operations are also highly cyclical. Refinancing activity can increase when interest rates fall, while delinquency and loss-mitigation activity can increase during periods of economic pressure. Maintaining a permanent domestic workforce large enough to handle peak volumes can leave companies overstaffed during slower periods.
Outsourcing provides an alternative by allowing businesses to increase or decrease operational capacity according to demand.
Why Pakistan for Mortgage BPO?
Pakistan has developed a large outsourcing and business-services industry supporting international companies across finance, customer service, IT, healthcare, insurance and other sectors.
For US mortgage companies, Pakistan can provide access to English-speaking professionals who can be trained on specific servicing workflows and client systems.
The time-zone difference can also support an overnight processing model. Back-office teams can process documents, update records and complete other operational tasks while US teams are outside their normal working hours. Teams supporting live borrower interactions can also be scheduled to overlap with US business hours.
Cost is another important factor. The page estimates potential savings of approximately 50–65% compared with US in-house staffing, depending on the role and engagement structure.
Mortgage Payment Processing
Payment processing is one of the most practical areas to outsource.
A mortgage payment processing team can support activities such as posting borrower payments, managing partial payments, handling suspense accounts and maintaining accurate servicing records.
Accuracy is critical because payment-posting errors can affect borrower balances and account histories.
A professional mortgage BPO provider should therefore use structured QA procedures and activity logging to monitor payment-processing accuracy.
For US mortgage companies considering mortgage servicing BPO outsource to Pakistan, payment processing can be an effective starting point before expanding into more complex servicing activities.
Escrow Administration
Escrow management is another important mortgage servicing function.
Outsourced escrow specialists can support annual escrow analysis, property tax and insurance disbursements, shortage or surplus notifications and related administrative tasks.
Because escrow calculations and communications can directly affect borrowers, teams should receive mortgage-specific training rather than relying solely on general financial-services experience.
Companies should also establish clear quality metrics for escrow processing, including error rates and turnaround times.
Document Processing and Indexing
Mortgage servicing generates substantial volumes of documents.
Documents need to be received, classified, indexed and attached to the correct loan file. When these activities are handled manually by expensive domestic employees, backlogs can develop quickly.
A Pakistan-based document processing team can provide dedicated capacity for high-volume mortgage documentation.
This can be particularly useful during servicing transfers, portfolio acquisitions, or periods when document volumes increase unexpectedly.
Mortgage Customer Service
Borrowers regularly contact mortgage servicers about payment histories, statements, payoff information, account questions and other servicing issues.
A dedicated mortgage customer service team can handle routine inquiries using client-approved scripts, systems, escalation procedures and workflows.
The goal is not simply to answer calls but to provide accurate information while identifying issues that require escalation to licensed or specialized US-based personnel.
Mortgage-specific training is important because borrower communication involves terminology and processes that general customer service representatives may not understand.
Default Management and Loss Mitigation Support
Default management requires a higher level of process awareness and compliance sensitivity.
A specialized BPO team can support delinquency tracking, early-stage borrower outreach, loss mitigation application processing, forbearance documentation, repayment-plan administration and related coordination.
However, offshore teams must operate within clearly defined boundaries.
Licensed US personnel should retain responsibility for activities that legally require licensed involvement, including applicable credit decisions, licensed loan origination activity and final loss-mitigation or servicing decisions.
Mortgage Refinancing Support
Refinancing is highly sensitive to interest-rate movements.
When rates fall, refinance applications can increase rapidly. A lender that does not have enough staff can face processing delays or struggle to respond to increased borrower demand.
Outsourced refinancing support can provide additional capacity for:
-
Application intake coordination
-
Document collection
-
Verification status tracking
-
Condition-clearing support
-
Borrower status communication
-
Administrative coordination with underwriting teams
This makes offshore capacity particularly valuable for businesses that experience significant fluctuations in refinance volumes.
Why Hire a Dedicated Mortgage Loan Processing Team in Pakistan?
For companies with consistent mortgage volumes, a dedicated team can provide greater continuity than hiring individual contractors for separate tasks.
Businesses can hire a dedicated mortgage loan processing team in Pakistan consisting of mortgage processing specialists, document processors, customer service representatives, QA professionals and team leads.
A dedicated team can become familiar with the client's:
-
Loan servicing platform
-
Internal procedures
-
Investor requirements
-
Escalation process
-
Documentation standards
-
Quality expectations
-
Reporting requirements
Over time, this accumulated process knowledge can improve consistency and reduce the need to repeatedly train new personnel.
Mortgage BPO Cost Comparison
The InLinkers page provides the following indicative comparison:
|
Mortgage Role |
US Monthly Cost |
Pakistan Monthly Cost |
|
Payment Processing Specialist |
$3,800–$5,600 |
$1,300–$2,000 |
|
Escrow Specialist |
$4,000–$5,900 |
$1,400–$2,150 |
|
Default/Loss Mitigation Specialist |
$4,500–$6,500 |
$1,600–$2,400 |
|
Document Processing Specialist |
$3,500–$5,000 |
$1,150–$1,750 |
|
Mortgage Customer Service Agent |
$3,700–$5,300 |
$1,250–$1,850 |
|
Refinance Support Specialist |
$4,000–$5,700 |
$1,400–$2,050 |
The source estimates that a 10-person mortgage servicing support team could produce approximately $290,000–$460,000 in annual savings compared with equivalent domestic staffing. These are indicative figures and actual costs vary by role, experience, workflow and engagement structure.
Compliance and Data Security
Mortgage outsourcing should never begin with cost comparison alone.
Before borrower information is transferred, US mortgage companies should establish appropriate contractual and security controls.
A structured engagement should include:
-
A mutual NDA
-
Data processing agreement
-
Role-based system access
-
Encrypted data transmission and storage
-
Activity and access logging
-
Documented breach procedures
-
Defined offshore responsibilities
-
Clear boundaries around licensed activities
The outsourcing partner should also be able to demonstrate where the team works and how physical and digital access to mortgage information is controlled.
How to Choose a Mortgage BPO Partner
Before signing an agreement, mortgage companies should verify several important factors.
Ask the provider for:
-
A named, access-controlled facility
-
PSEB or SECP registration details
-
Mortgage-specific staff training information
-
A data processing agreement
-
Client-led team interviews
-
Sample-file audit capabilities
-
Named backup specialists
-
Mortgage-specific QA reports
-
Defined escalation procedures
-
Clear documentation of licensed-activity boundaries
These checks help separate specialized mortgage BPO providers from general outsourcing companies that simply add "mortgage support" to their service list.
Getting Started With a Dedicated Mortgage Team
A structured onboarding process can allow a mortgage business to establish offshore support without a lengthy recruitment cycle.
The InLinkers model describes a 14-day process that includes discovery and NDA signing, data-processing documentation, candidate profiles, client interviews, sample-file audits, agreement execution, system access, workflow-specific training and a supervised initial batch before independent operations begin.
This approach allows the client to evaluate the team before moving fully into production.
Final Thoughts
Mortgage servicing requires accuracy, consistency, security and specialized knowledge. For US lenders, servicers and mortgage technology companies, outsourcing selected processes can provide additional operational capacity while reducing the cost of maintaining a large domestic workforce.
When businesses mortgage servicing BPO outsource to Pakistan, they can access specialists for payment processing, escrow administration, document management, customer service, default support and refinancing operations.
For companies with ongoing volumes, the option to hire a dedicated mortgage loan processing team in Pakistan can provide greater continuity, scalability and process familiarity.
The most important factor is choosing a partner that understands mortgage workflows and treats compliance and data protection as core requirements. With proper due diligence, clear contractual boundaries, mortgage-specific training and structured quality controls, Pakistan can provide a scalable offshore extension of a US mortgage operation.
- Managerial Effectiveness!
- Future and Predictions
- Motivatinal / Inspiring
- Fitness and Wellness
- Medical & Health
- Manufacturing
- Education
- Real-Estate
- Food Industry
- Hospitality
- Online Games
- Sports
- Home Services
- Civil Engineering
- Safety and Protection
- Software Products & Services
- Fashion and Jewellery
- Artificial Intelligence
- Entrepreneurship
- Mentoring & Guidance
- Marketing
- Networking
- HR & Recruiting
- Literature
- Shopping
- Career Management & Advancement