 SkillClick
How Financing Terms Differ for Dodge and Jeep Buyers
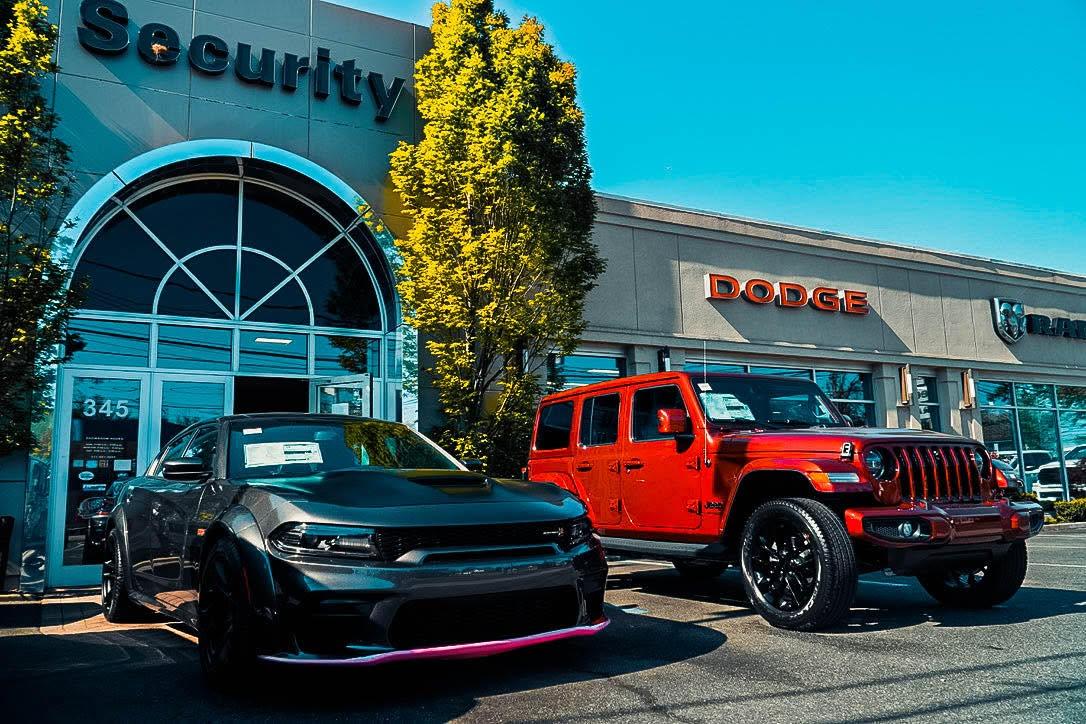
Buying a vehicle is never just about the sticker price. The loan terms, interest rate, down payment, and repayment period can change the real cost of ownership in a major way. That is especially true when comparing Dodge and Jeep buyers, because these two brands tend to attract different kinds of drivers with different borrowing profiles, vehicle uses, and financing priorities. In many cases, a shopper comparing models at a Chrysler Dodge Jeep Ram Dealer Long Island will notice that the financing conversation shifts depending on whether they are looking at a performance-focused Dodge or a utility-driven Jeep.
Understanding those differences can help buyers make smarter decisions before they sign anything. While both brands often come from the same lender network and may qualify for similar programs, the way financing terms play out can vary based on vehicle type, buyer credit, trade-in value, and intended use. Knowing what to expect can make the process less stressful and more transparent.
Key points
- Dodge and Jeep buyers often face different loan terms because the vehicles serve different purposes and appeal to different borrowers.
- Interest rates, down payments, and loan lengths can vary based on credit history, resale value, and model demand.
- Jeep financing may reflect off-road capability and higher trim pricing, while Dodge financing may be shaped by performance models and sports-car style depreciation.
- Lease offers, manufacturer incentives, and seasonal promotions can affect each brand differently.
- Comparing total loan cost, not just monthly payment, is essential for both Dodge and Jeep shoppers.
Why Financing Terms Are Not the Same for Every Buyer
Auto financing is based on risk. Lenders look at the vehicle, the borrower, and the expected resale value when deciding how to structure a loan. Even if two people have the same credit score, they may receive different financing terms if one is buying a Dodge Charger and the other is buying a Jeep Wrangler. The reason is simple. These vehicles depreciate differently, are used differently, and attract different buyers.
Dodge models are often associated with performance, speed, and street-oriented driving. Jeep models are usually linked to adventure, utility, and four-wheel-drive capability. Those differences matter to lenders because they influence how well the vehicle holds value and how easy it would be to resell if the borrower defaults.
How Dodge Financing Terms Typically Compare
Performance Models and Depreciation
Dodge vehicles, especially performance-oriented trims, often carry strong appeal at purchase but may depreciate faster than some utility vehicles. Lenders know this. A car that loses value quickly can create more risk for the lender, which sometimes leads to stricter loan terms, shorter repayment periods, or higher interest rates for certain buyers.
For example, a buyer financing a Dodge Charger or Dodge Challenger may see terms that differ from those offered on a more mainstream sedan. Even within the Dodge lineup, a high-horsepower trim may be treated differently from a family-oriented model like the Durango.
Loan Length and Monthly Payment Trade-Offs
Many Dodge buyers focus on keeping the monthly payment manageable, especially when financing a vehicle with a higher trim level or added performance packages. A longer loan term can reduce the monthly bill, but it also increases the total interest paid over time. Since performance vehicles can lose value faster, a long-term loan can sometimes create negative equity, where the borrower owes more than the car is worth.
That is why some lenders may prefer shorter terms on certain Dodge vehicles. A 60-month loan may be more common than a 72-month or 84-month structure for a performance model, depending on the buyer’s credit and the lender’s policies.
How Jeep Financing Terms Typically Compare
Utility, Resale Value, and Borrower Appeal
Jeep models often hold value well because of their broad market appeal, especially vehicles like the Wrangler and Grand Cherokee. Lenders tend to appreciate strong resale value because it lowers their risk. That can sometimes translate into competitive financing offers, particularly for buyers with solid credit.
Jeep buyers may also have access to different financing structures because the brand attracts drivers who want versatility. A Jeep might be used for commuting, family travel, or outdoor recreation. Lenders may view the vehicle as practical and durable, which can support favorable loan terms in some cases.
Higher Trims and Optional Equipment
Although some Jeep models hold value well, their higher trims can become expensive quickly. Off-road packages, advanced safety tech, upgraded interiors, and four-wheel-drive systems can raise the financing amount significantly. A buyer selecting a fully equipped Jeep may see terms that look different from a base model, simply because the total amount financed is larger.
In those cases, the monthly payment may remain reasonable if the borrower chooses a longer term. However, a longer term can also mean more interest over the life of the loan. Buyers should compare how each term affects the full cost, not just the payment amount.
Credit Score Still Plays a Major Role
Whether buying a Dodge or a Jeep, credit score remains one of the biggest factors in financing terms. A borrower with excellent credit may receive a lower rate, fewer fees, and more flexible repayment options. A borrower with fair or limited credit may still qualify, but the terms are likely to be less favorable.
This is where brand differences can become less important than individual financial history. A strong credit profile can offset some of the concerns a lender may have about depreciation or vehicle type. On the other hand, weaker credit can make financing more expensive even for a model with strong resale value.
Before applying, buyers should review their credit report, pay down revolving balances if possible, and avoid opening new debt accounts right before financing. These steps can improve the terms they are offered.
Down Payments and Trade-Ins Can Shift the Terms
A larger down payment reduces the amount financed and can improve the lender’s view of the deal. This is especially useful for Dodge buyers financing performance vehicles or Jeep buyers selecting high-end trims. The more money put down up front, the less risk the lender carries.
Trade-ins also matter. If a buyer has a vehicle with strong equity, that value can be applied toward the new purchase and reduce the loan balance. This may help the borrower qualify for better terms or a shorter loan period.
For many shoppers, the smartest strategy is not simply choosing the lowest monthly payment. It is balancing down payment, trade-in value, rate, and term length to create a loan that fits the budget without stretching the debt too far.
Lease Terms Can Differ Too
Leasing is another area where Dodge and Jeep buyers may see differences. Lease offers are often based on projected resale value, expected mileage, and model demand. A Jeep with strong residual value may produce an attractive lease structure. A Dodge performance vehicle may lease differently because of its pricing and depreciation pattern.
Leases also come with mileage limits, wear-and-tear expectations, and end-of-term fees. Buyers who drive a lot or plan to modify their vehicle should pay close attention to those details. Jeep drivers who use their vehicle for road trips or off-road use may find lease restrictions more limiting than a traditional loan.
Manufacturer Incentives and Seasonal Offers
Financing terms can also shift based on current incentives. Manufacturers sometimes offer low APR financing, cashback offers, or special lease rates on selected Dodge and Jeep models. These promotions are not always available across the entire lineup. One model may qualify while another does not.
Timing can make a difference as well. End-of-month, end-of-quarter, and year-end sales periods sometimes bring stronger offers. Buyers should compare the incentive with the actual loan structure to make sure the deal is truly beneficial. A low advertised rate can still be expensive if the vehicle price is inflated or the term is too long.
Practical Tips for Buyers Comparing Dodge and Jeep Loans
- Compare the annual percentage rate, not just the monthly payment.
- Ask how the loan term affects total interest paid.
- Review the vehicle’s estimated resale value before choosing a long-term loan.
- Consider whether a larger down payment could reduce long-term costs.
- Check for rebates or special financing offers tied to specific models.
- Use a loan calculator to compare different term lengths side by side.
- Read the contract carefully for fees, prepayment terms, and add-ons.
Conclusion
Financing terms for Dodge and Jeep buyers are shaped by more than brand name alone. Vehicle type, resale outlook, loan amount, borrower credit, and available incentives all play a role. Dodge shoppers may encounter terms influenced by performance and depreciation, while Jeep buyers may see terms shaped by utility, strong resale value, and higher trim pricing. In both cases, the best approach is to look beyond the monthly payment and focus on the full cost of borrowing.
By comparing rates, reviewing loan length, and understanding how each model affects lender risk, buyers can make better decisions and avoid paying more than necessary. Whether the goal is a powerful Dodge or a capable Jeep, informed financing choices can make the purchase more manageable and more rewarding over time.
FAQ
Do Dodge and Jeep buyers get different interest rates?
Yes, sometimes. Rates can differ based on the vehicle, loan amount, credit score, and lender risk. A performance Dodge and a high-value Jeep may be treated differently by lenders.
Which brand usually has better financing terms?
There is no universal answer. Jeep may benefit from stronger resale value, while Dodge may qualify for competitive incentives on certain models. The best terms depend on the exact vehicle and the buyer’s credit profile.
Are longer loan terms a good idea?
Longer terms lower the monthly payment, but they usually increase total interest paid. They can also create negative equity if the vehicle depreciates faster than the loan balance decreases.
Does a bigger down payment help with either brand?
Yes. A larger down payment reduces the amount financed and may lead to better terms. It can be especially helpful for higher-priced Dodge or Jeep trims.
Should buyers choose financing or leasing?
It depends on driving habits and ownership goals. Financing is usually better for long-term ownership, while leasing may suit drivers who want lower monthly payments and plan to change vehicles often.
What should shoppers compare before signing?
Buyers should compare APR, loan term, total interest, fees, down payment, trade-in value, and any incentives. Looking at the full picture helps reveal the true cost of the vehicle.
- Managerial Effectiveness!
- Future and Predictions
- Motivatinal / Inspiring
- Fitness and Wellness
- Medical & Health
- Manufacturing
- Education
- Real-Estate
- Food Industry
- Hospitality
- Online Games
- Sports
- Home Services
- Civil Engineering
- Safety and Protection
- Software Products & Services
- Fashion and Jewellery
- Artificial Intelligence
- Entrepreneurship
- Mentoring & Guidance
- Marketing
- Networking
- HR & Recruiting
- Literature
- Shopping
- Career Management & Advancement